
Family Bank nine-month profit jumps 69pc to Sh6.07bn on stronger lending
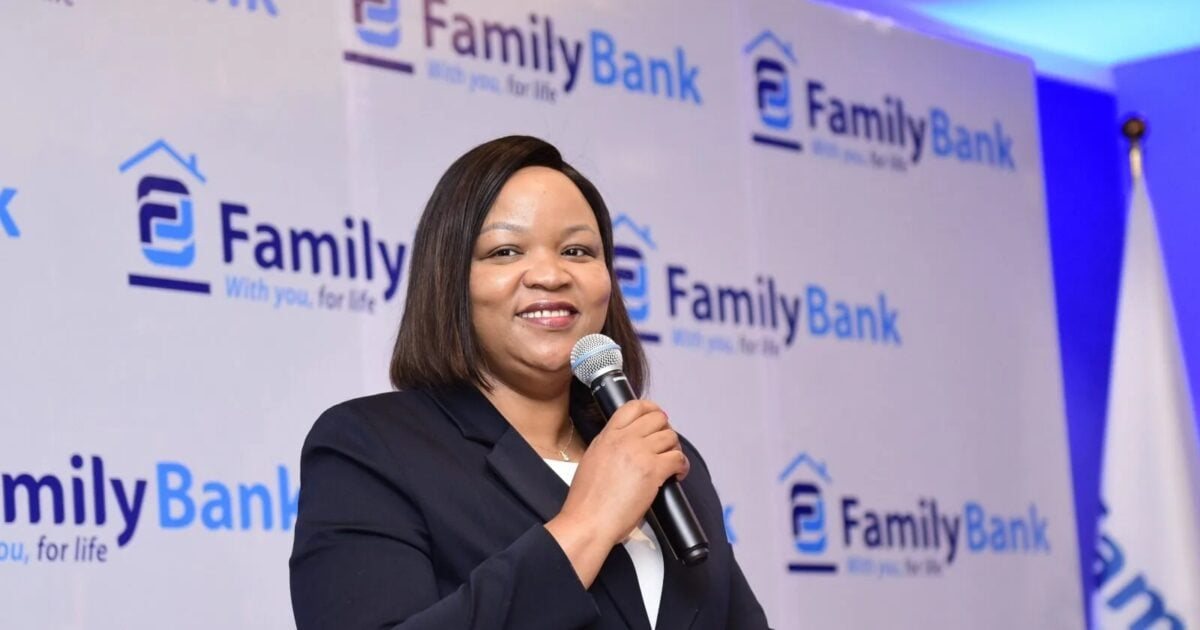
Family Bank Group's after-tax profit rose 69 percent to Sh6.07 billion in the nine months to September 2026, according to Capital FM Business. Higher interest income and an expanded loan book drove the gain.
The figure is up from Sh3.60 billion in the same period a year earlier. The unaudited results are the first covering the lender's time as a company listed on the Nairobi Securities Exchange.
Profit before tax increased 62 percent to Sh7.26 billion, compared with Sh4.50 billion previously.
Interest income drives growth
Total operating income rose 26 percent to Sh18.64 billion from Sh14.74 billion. Net interest income was the main contributor, growing 37 percent to Sh15.02 billion.
Gross interest income reached Sh22.03 billion, up from Sh17.72 billion. Of this, loans and advances generated Sh13.14 billion, while government securities brought in Sh8.48 billion.
Non-interest income, which covers fees, commissions and foreign exchange earnings, fell slightly to Sh3.62 billion from Sh3.79 billion a year earlier.
Costs and asset quality
Operating expenses climbed 11 percent to Sh11.39 billion from Sh10.24 billion.
Loan loss provisions rose 27 percent to Sh1.73 billion from Sh1.36 billion. The increase reflects more money set aside against possible credit losses.
The bank's gross non-performing loans grew to Sh18.93 billion from Sh15.60 billion. Net non-performing loans almost doubled to Sh5.93 billion from Sh3.32 billion, Capital FM Business reported. This points to continued pressure on asset quality despite the profit growth.
Balance sheet expands
Total assets rose 22 percent to Sh247.54 billion from Sh202.59 billion.
Customer loans and advances grew 14 percent to Sh118.20 billion. Customer deposits increased faster, rising 24 percent to Sh182.35 billion from Sh146.84 billion and giving the bank more money to lend.
The lender said it disbursed more than Sh91 billion to the private sector during the period. More than 70 percent of that went to micro, small and medium enterprises (MSMEs) and consumer banking customers.
Shareholders' funds grew 29 percent to Sh36.43 billion.
The bank's capital and liquidity positions remained well above regulatory requirements:
- Liquidity ratio: 61.6 percent, against a statutory minimum of 20 percent
- Total capital to risk-weighted assets: 18 percent, against a regulatory minimum of 14.5 percent
Listing marks new chapter
Chief Executive Officer Nancy Njau said the results showed the strength of the bank's strategy and the confidence of its customers.
She said the listing on the Nairobi bourse had opened a new phase for the lender. She described it as being built on a firmer commitment to transparency, accountability and long-term value for shareholders.
"Our focus remains on delivering innovative financial solutions and exceptional service," Ms Njau said.
She added that the bank would keep investing in its staff, technology and distribution network. Its retail, MSME and commercial banking segments remain its core focus.
The results give investors their first look at Family Bank's performance as a publicly traded lender.
This story was prepared by the Hamasta Newsdesk with AI assistance, based on reporting by Capital FM Business. Read the original report. Photo: Capital FM Business.


Grow an audience that listens.
Social media management, digital campaigns and online storytelling that converts.


More in Business
See all
KUSCCO Mutual Assurance Statutory Management Extended to December 31
Equity Group nine-month profit rises 32pc to Sh71.5bn on income growth
Treasury Proposes Car Loan and Mortgage Fund for TSC Secretariat Staff
Nigerian fintech Payaza enters Kenya after securing CBK payment licence
Kenya Industrial Estates opens 38 permanent jobs, applications close December 9
Global Community Remarks
0