
Sh700 billion moved in a year, and now every exchange needs a licence: What Kenya's new crypto rules mean for your wallet
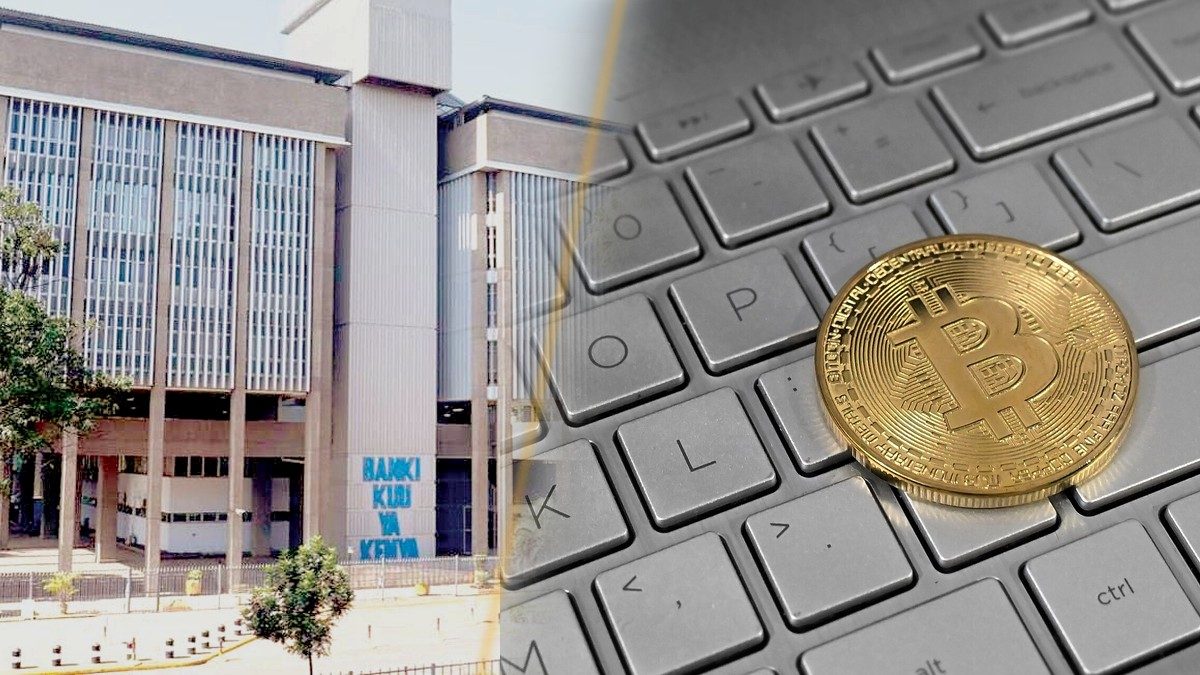
For years, a Kenyan who lost money on a crypto app had almost nowhere to complain. From this month, the business on the other side of that app is supposed to hold a licence, and there are two regulators whose job is to ask it hard questions.
In a joint public notice dated Friday, November 13, the Central Bank of Kenya (CBK) and the Capital Markets Authority (CMA) said anyone "providing or intending to provide virtual asset services" must apply for a licence from the relevant regulator. The notice confirmed that the Virtual Asset Service Providers (VASP) Regulations, 2026, were gazetted on July 22 as Legal Notice No. 134, completing the rule book under the VASP Act, 2025.
How we got here
The VASP Act was gazetted on October 21, 2025, and came into force on November 4, 2025. Businesses already in the market were given a one-year transition period to comply. That window closed on November 4, 2026.
The market being regulated is not small. Figures from analytics firm Chainalysis, cited by Kenyans.co.ke, show Kenyans moved digital assets worth about Sh700 billion in the year to June 2026, up from Sh506 billion a year earlier.
Two referees, one market
The law splits supervision according to what a business does, as People Daily reports from the notice:
- CBK: virtual asset wallet providers, payment processors and stablecoin issuers.
- CMA: virtual asset exchanges, brokers, investment advisers, managers and other investment-related services.
An analysis of the gazetted regulations by law firm TL Advocates counts ten licence categories across the two regulators. It says a regulator has up to 30 days to decide on a complete application, licences are renewed every year, and a licensed firm must start business within 12 months.
Entry is not cheap. The same analysis puts the minimum paid-up capital for a stablecoin issuer at Sh300 million and for a wallet provider at Sh150 million, with most other categories set lower than in the earlier draft rules.
What a licensed provider must do for you
The regulations borrow heavily from banking and stockbroking rules. According to the law firm's summary, a licensed provider must:
- verify a customer's identity before opening an account, in line with anti-money laundering law;
- keep records of all activity on its platform for at least seven years;
- keep the crypto business in a separate unit with its own management and books of account;
- put customers' interests first where there is a conflict of interest, and disclose it.
Stablecoins, the tokens designed to hold a steady value against a currency such as the US dollar, get the tightest treatment. Every coin in issue must be fully backed by reserve assets kept apart from the issuer's own money, the issuer may not pay interest on it, and a holder may redeem at par at any time, with payment due within two working days. No stablecoin may be listed on a Kenyan platform unless CBK has approved it.
What the rules do not do
A licence is not a guarantee of profit. People Daily's assessment of the framework notes that prices of digital assets remain volatile and that customers can still lose money through market swings or cyberattacks. A licence tells you a firm has been vetted, not that the coin it sells will hold its value.
The rules could also thin out the market. Capital and compliance costs may favour large, well-funded companies over small local start-ups, and some providers may leave rather than apply. The reports on the notice give no figure for applications received so far, and the regulators say lists of licensed firms will be published once approvals are issued.
What to do now
- Before sending money to an exchange, wallet or payment app, check whether it appears on the lists of licensed providers that CBK and CMA have promised to publish.
- Ask your provider which regulator it has applied to. A wallet or payment service should be dealing with CBK; an exchange or broker with the CMA.
- Be wary of any firm that claims to be "approved" before those lists exist.
- Keep your own records of deposits, trades and withdrawals.
What comes next
Kenyans.co.ke reports that the National Treasury is also considering, in a draft Unclaimed Financial Assets National Policy, whether dormant cryptocurrencies and stablecoins should be surrendered to the Unclaimed Financial Assets Authority in the same way as forgotten bank accounts and shares. That proposal is still at the draft stage. For now, the practical test of the new regime will be the first published list of who is licensed, and who is not.
Photos: People Daily (Central Bank of Kenya headquarters, via @StocksMarket_ke/X); Satheesh Sankaran via Wikimedia Commons (CC BY 2.0). Thumbnail design: HAMASTA MEDIA.
Every moment, captured beautifully.
Events, corporate portraits, products and editorial shoots by our newsroom photographers.




More in Technology
See all
Kenya's Data Commissioner Immaculate Kassait Wins Global Buttarelli Privacy Award
Voyager 1 becomes first human-made object to sit a full light-day from Earth
Kenya retains ITU Council seat with highest vote tally among African nations
'That mountain has been causing you problems': Ruto promises four lanes for the jam-choked Rironi-Mai Mahiu escarpment road
'Huyu ni mwizi': Stabbed and robbed of his phone, Nairobi techie builds a remote that makes a snatched handset scream at the thief
From 14 days to under five minutes: DCI's biometric system for good conduct certificates reaches Uasin Gishu, Trans Nzoia, Kitui and Garissa
Global Community Remarks
0