Kenya's forex reserves slip to 5.9 months of import cover as oil prices climb
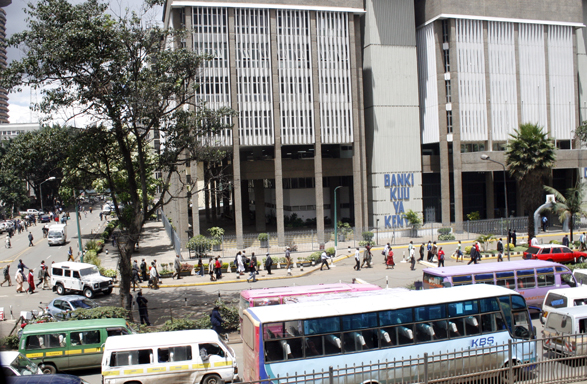
Kenya's official foreign exchange reserves have fallen below six months of import cover for the first time in weeks, according to the Central Bank of Kenya's (CBK) latest weekly bulletin.
Reserves stood at US$14,736 million as of October 8, 2026, equivalent to 5.9 months of import cover. That was down from US$14,930 million, or 6.1 months, on October 1, a drop of about US$194 million in a single week.
A steady decline since September
The bulletin shows a gradual slide over the past month:
- September 10: US$15,253 million (6.3 months)
- September 17: US$15,088 million (6.1 months)
- September 24: US$15,042 million (6.1 months)
- October 1: US$14,930 million (6.1 months)
- October 8: US$14,736 million (5.9 months)
The CBK said reserves "remained adequate" and continue to meet its statutory requirement to endeavour to maintain at least four months of import cover. Import cover is calculated using a 36-month average of imports of goods and non-factor services.
Oil prices in the background
The dip comes as global energy prices rise. The CBK noted that Murban crude climbed to US$101.67 a barrel on October 8 from US$95.76 a week earlier, driven by supply concerns linked to geopolitical tensions in the Middle East. Higher oil prices increase the dollars Kenya needs to pay for fuel imports and are expected to widen the current account deficit this year.
The shilling has so far held steady, trading at Ksh129.94 to the US dollar on October 8 compared with Ksh129.71 on October 1.
At its meeting on October 7, the CBK's Monetary Policy Committee kept the Central Bank Rate unchanged at 8.75 per cent, noting that global inflationary pressures had increased because of higher energy and food prices but that domestic inflation was expected to remain within the target range, supported in part by a stable exchange rate.
What it means for Kenyans
Healthy reserves act as a buffer that allows the central bank to smooth sharp swings in the shilling and reassures investors and lenders that the country can meet its external obligations. At 5.9 months, cover remains well above the four-month statutory floor. A sustained decline, however, could put pressure on the shilling, making imported goods such as fuel, cooking oil and machinery more expensive.
What next
Analysts will watch upcoming weekly bulletins for signs of whether the drawdown continues, particularly if crude prices stay above US$100 a barrel and as the government meets external debt repayments in the coming months.
Photo: DEMOSH / Wikimedia Commons, CC BY 2.0
Every moment, captured beautifully.
Events, corporate portraits, products and editorial shoots by our newsroom photographers.
More in Business
See all
Kirima's widow warns Kenyans against buying plots on disputed 1,000-acre Njiru land

Kenya woos foreign building materials makers to set up factories and boost affordable housing
Bankers push for PAYE cut for all workers as Ruto targets low earners
Second shipment of heavy machinery for Dangote refinery docks at Lamu port

UK government arm takes Sh1.94bn stake in Quickmart IPO
Six oil tankers among 51 ships expected at Mombasa and Lamu ports by end of October
Global Community Remarks
0